Introduction
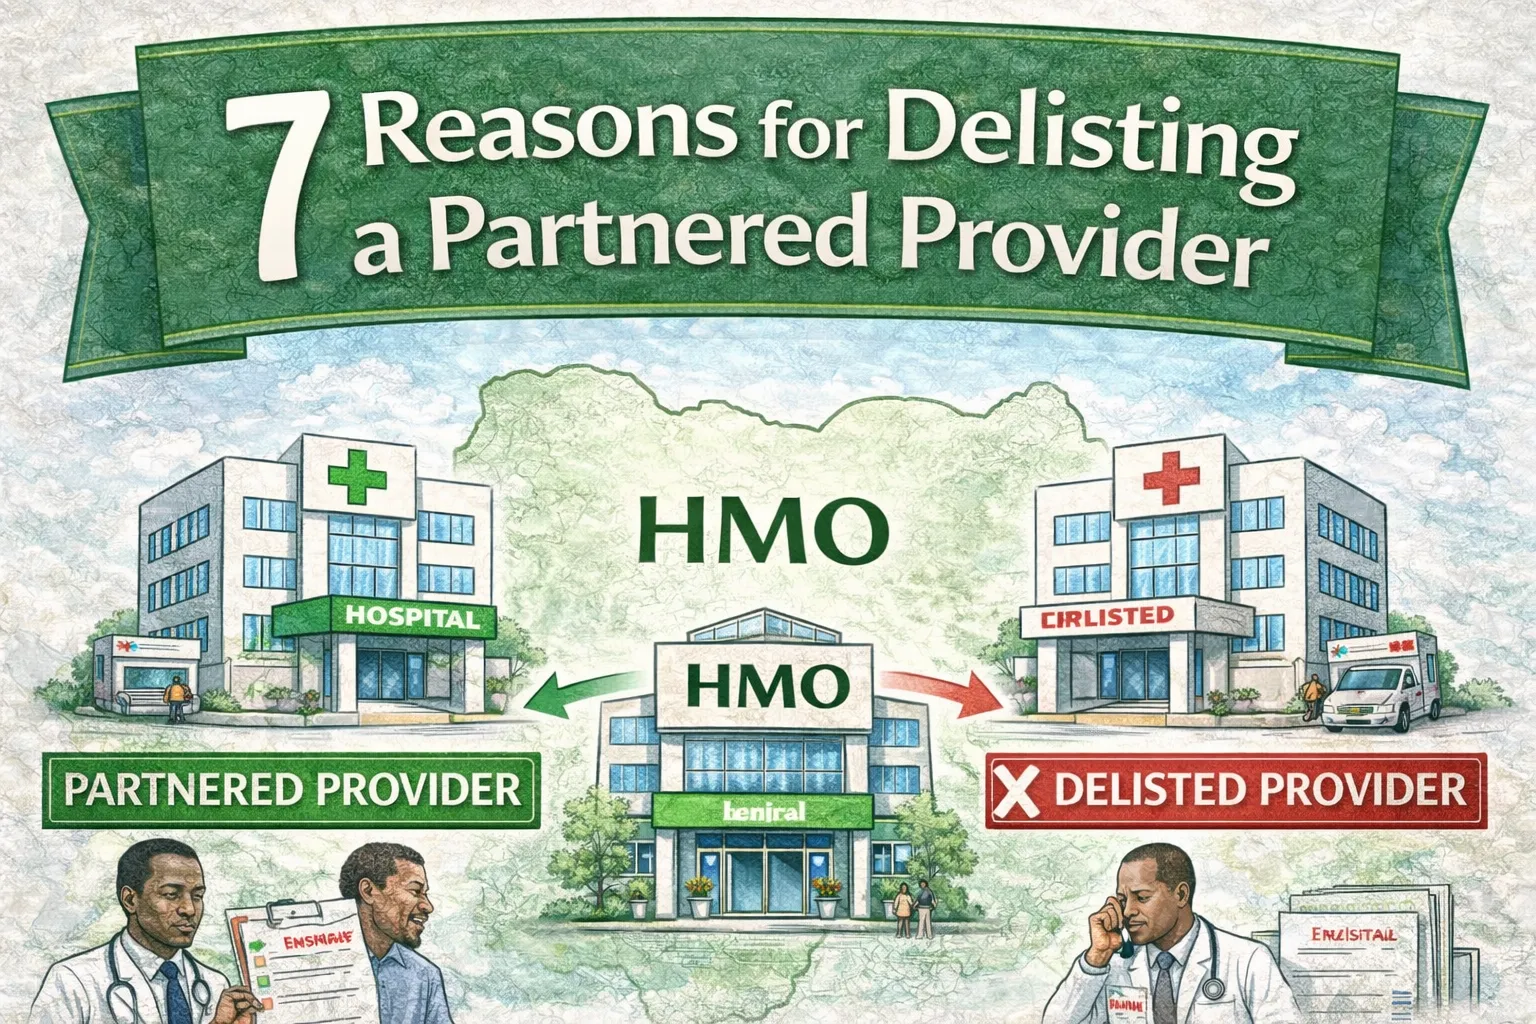
The phrase 7 Reasons Why an HMO May Delist a Partnered Provider may sound technical at first. But if you have ever logged into your HMO portal and noticed your preferred hospital missing from the list, you already understand how personal this topic can feel.
You might think:
Did something go wrong?
Is the hospital unsafe?
Is my insurance about to fail me?
Let us pause and bring clarity.
Provider networks are not static. They evolve. They expand. They shrink. Contracts are signed and renewed. Audits are conducted. Performance is evaluated. And sometimes, a provider is removed from the network.
.Understanding the 7 Reasons Why an HMO May Delist a Partnered Provider gives you confidence instead of anxiety. It shifts your mindset from fear to informed awareness.
Let us explore each reason deeply, practically, and honestly.
1 Breach of Contractual Obligations
At the heart of every HMO provider relationship is a contract. Not a handshake. Not a verbal promise. A formal agreement.
This agreement defines:
How much the HMO will pay for specific treatments
How claims must be documented
How patients should be treated
How billing disputes will be handled
Quality assurance expectations
Confidentiality standards
When a provider signs that contract, it agrees to operate within that structure.
What a Contract Breach Looks Like in Real Life
Imagine this scenario.
An HMO agrees to pay a fixed amount for cesarean delivery procedures. Over time, the hospital begins charging insured patients additional “facility upgrade” fees that were never part of the agreement.
Patients start complaining. The HMO investigates and confirms the pattern.
First, the hospital receives a warning.
Then, corrective meetings are held.
If the behavior continues, the contract may be terminated.
This becomes one of the 7 Reasons Why an HMO May Delist a Partnered Provider.
Insurance systems rely heavily on predictability. If pricing becomes inconsistent, the entire network becomes unstable.
Trust is broken. And once trust breaks, partnership becomes difficult to maintain.
2 Persistent Poor Quality of Care
No HMO wants its members treated in unsafe conditions.
Quality monitoring is continuous. HMOs track:
Clinical outcomes
Infection rates
Surgical complications
Patient satisfaction reports
Audit results
Staff credential compliance
Let us make this relatable.
Suppose three insured patients report similar post surgery complications at the same hospital. An audit reveals inadequate sterilization practices. Equipment maintenance logs are incomplete.
The HMO now faces a serious decision.
Continue the relationship and risk patient harm?
Or remove the hospital from the network?
Patient safety always takes priority.
This is why poor clinical performance is one of the strongest of the 7 Reasons Why an HMO May Delist a Partnered Provider.
Sometimes delisting protects lives.
3 Financial Disputes and Rate Negotiation Breakdowns
Healthcare is both service and business.
Hospitals face rising costs. Inflation affects:
- Medical supplies
- Imported equipment
- Electricity
- Staff salaries
Meanwhile, HMOs must maintain affordable premiums for members.
Here is a practical example.
An HMO negotiates maternity service rates with a private hospital. After one year, the hospital demands a 40 percent increase in reimbursement fees. The HMO argues that such an increase would force premium hikes.
Negotiations stall.
The contract expires.
The hospital is delisted.
No scandal. No negligence. Just financial disagreement.
This is one of the most common and misunderstood of the 7 Reasons Why an HMO May Delist a Partnered Provider.
It is about sustainability.
4 Regulatory and Licensing Problems
Healthcare providers must maintain compliance with government regulations.
If a hospital:
Loses its operating license
Fails regulatory inspection
Faces suspension
Becomes involved in legal investigation
The HMO may suspend or terminate the partnership immediately.
Insurance companies cannot risk associating with legally compromised institutions.
Regulation protects enrolled members.
5 Repeated Member Complaints
Feedback matters more than many people realize.
Imagine this pattern:
Insured patients report rude front desk staff.
They report being asked to pay for covered services.
They report long delays in treatment verification.
One complaint is manageable.
Ten complaints signal a pattern.
HMOs conduct performance reviews. If corrective measures fail, delisting becomes necessary.
Remember, an HMO’s reputation depends on member trust.
6 Low Utilization by Members
Sometimes delisting is purely strategic.
Maintaining a provider partnership involves:
System integration
Administrative oversight
Periodic audits
Contract renewals
If only two insured patients visit a hospital each month, maintaining the contract may not be efficient.
For example, an HMO once had strong membership in a semi urban area. Over time, most members relocate to metropolitan centers. That rural hospital sees minimal HMO traffic.
The HMO may restructure the network.
This is business optimization, not punishment.
7 Documentation and Claims Compliance Failures
Hospitals must submit:
- Diagnosis reports
- Treatment notes
- Correct coding
- Supporting medical evidence
If documentation is repeatedly incomplete, inconsistent, or suspicious, compliance risks increase.
For instance, if claims frequently lack proper justification, it may raise audit concerns.
Administrative discipline is crucial to system integrity.
This final factor completes the 7 Reasons Why an HMO May Delist a Partnered Provider.
What Delisting Actually Means for You
If your hospital is removed:
Your insurance remains valid.
You may need to select a new provider.
Ongoing treatment may require transition planning.
Most HMOs communicate changes in advance.
Stay informed.
How to Protect Yourself
Choose HMOs with broad networks.
Confirm alternative hospitals nearby.
Review provider lists annually.
Keep personal medical records.
FAQs
Should I panic if my hospital is suddenly delisted?
No, but you should act calmly and quickly.
When you see your hospital removed, your first reaction might be fear. You may imagine worst case scenarios. But delisting does not mean your insurance is collapsing.
Instead, contact your HMO immediately. Ask:
Why was the provider delisted?
When did this take effect?
What alternative hospitals are available near me?
If I am mid treatment, what arrangements are in place?
Often, there are structured transition policies. HMOs understand that patients cannot simply stop care abruptly.
Stay calm. Ask questions. Gather information before reacting emotionally.
What happens if I am pregnant and my maternity hospital is delisted
This is one of the most sensitive scenarios.
If you are mid pregnancy and your hospital is removed, immediately contact your HMO.
Many HMOs offer continuity of care policies. This means they may allow you to complete your maternity care at the same facility under temporary approval.
If not, they may recommend an alternative hospital within the network that provides similar maternity services.
The key is communication. The earlier you inform your HMO, the smoother the transition.
Never assume coverage continues automatically. Always confirm.
Can I continue seeing my doctor privately after delisting
Yes, but you may have to pay out of pocket.
If your preferred doctor practices at a delisted hospital, you can still consult them privately. However, insurance coverage may no longer apply unless special arrangements exist.
Some doctors may practice at multiple facilities. Ask whether they are affiliated with another hospital within your network.
Flexibility often exists if you ask.
How can I avoid being affected by network changes
You cannot control contracts. But you can reduce impact.
Choose HMOs with large, diversified networks.
Avoid plans with only one major hospital in your area.
Review network updates annually.
Stay informed about renewal periods.
Think of it like diversifying investments. More options equal less risk.
Does delisting affect premium costs
Indirectly, yes.
If delisting results from financial disputes, restructuring may stabilize costs. Removing expensive providers can prevent premium increases.
However, if network shrinkage reduces access significantly, member dissatisfaction may rise.
Insurance pricing reflects network balance.
How transparent are HMOs about delisting reasons
Transparency varies.
Some HMOs publish updates. Others communicate directly to affected members.
If clarity is lacking, request written explanation.
As a member, you have the right to ask.
Can an HMO reverse a delisting decision
Yes.
If financial negotiations succeed or compliance issues are resolved, providers may rejoin the network.
Delisting is not always permanent.
Conclusion
The 7 Reasons Why an HMO May Delist a Partnered Provider reflect the dynamic nature of healthcare networks.
Delisting can result from contract breaches, quality issues, financial disagreements, regulatory problems, complaint patterns, strategic restructuring, or documentation failures.
It is rarely random.
As a member, your power lies in awareness..
Review provider lists regularly.
Communicate proactively.
Insurance is about protection and access. Understanding network changes ensures you remain confident and informed rather than anxious and uncertain.
| |||||||||||
| Odilo Alexander (Editor-in-Chief) is a registered Nurse RN BSN trained at the University of Benin and licensed by the Nursing and Midwifery Council of Nigeria. With over eight years of experience across clinical and managed care settings including leadership roles in claims management and HMO operations, AOBLOG provides practical and evidence based wellness and health insurance education for Africa. |