Introduction
Everyone wants affordable healthcare. No one wants hospital bills that wipe out savings overnight. That is exactly why so many people search for How to Buy Cheap Health Insurance in Nigeria Without Regret.
But here is the truth most people discover too late.
Cheap can either mean smart… or dangerous.
Some people buy the lowest priced plan they see online, only to discover:
Their hospital is not covered.
Their surgery is excluded.
Their coverage cap is too small.
Their HMO is not even accredited.
Regret does not come from buying cheap health insurance.
Regret comes from buying blindly.
This guide will show you how to Buy Cheap Health Insurance in Nigeria Without Regret using smart, verified, practical steps that protect both your health and your wallet.
Now let us break this down the right way.
What Cheap Health Insurance Really Means in Nigeria
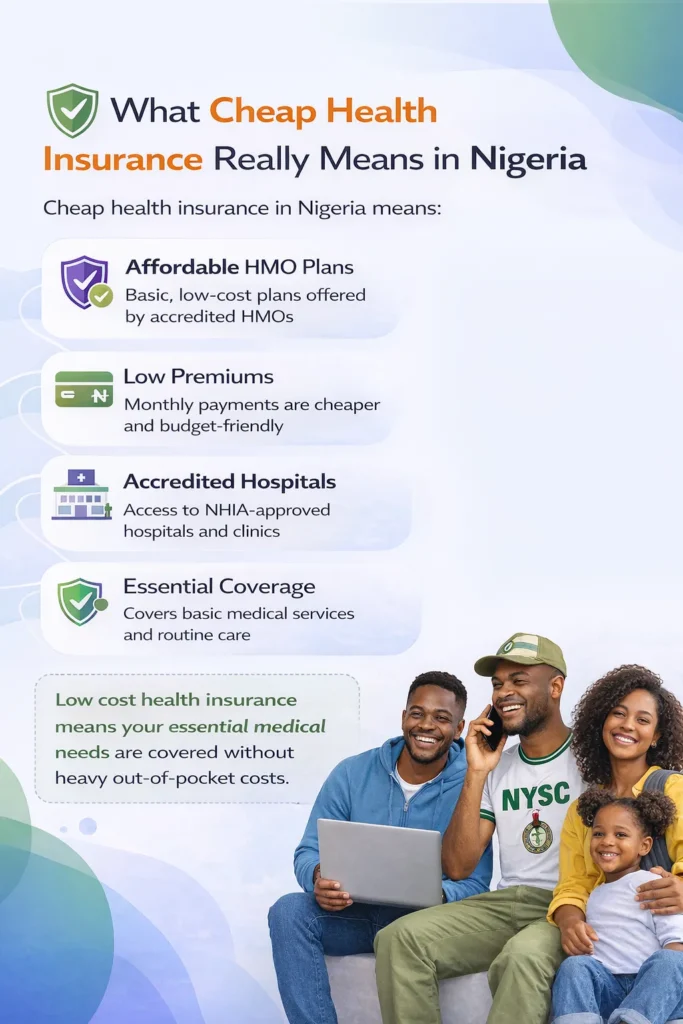
When most people say “cheap,” they mean low price.
But in health insurance, cheap should mean:
- Affordable premium
- Usable hospital access
- Reasonable inpatient limits
- Transparent benefit structure
- Regulated and accredited provider
In Nigeria, entry level HMO plans can appear very affordable. But price alone does not determine whether you will regret the decision later.
True affordability means:
You can actually use the coverage.
You are not shocked by hidden copayments.
The hospital near you accepts the plan.
Emergency admission is covered.
If you truly want to Buy Cheap Health Insurance in Nigeria Without Regret, you must focus on smart affordability, not emotional affordability.
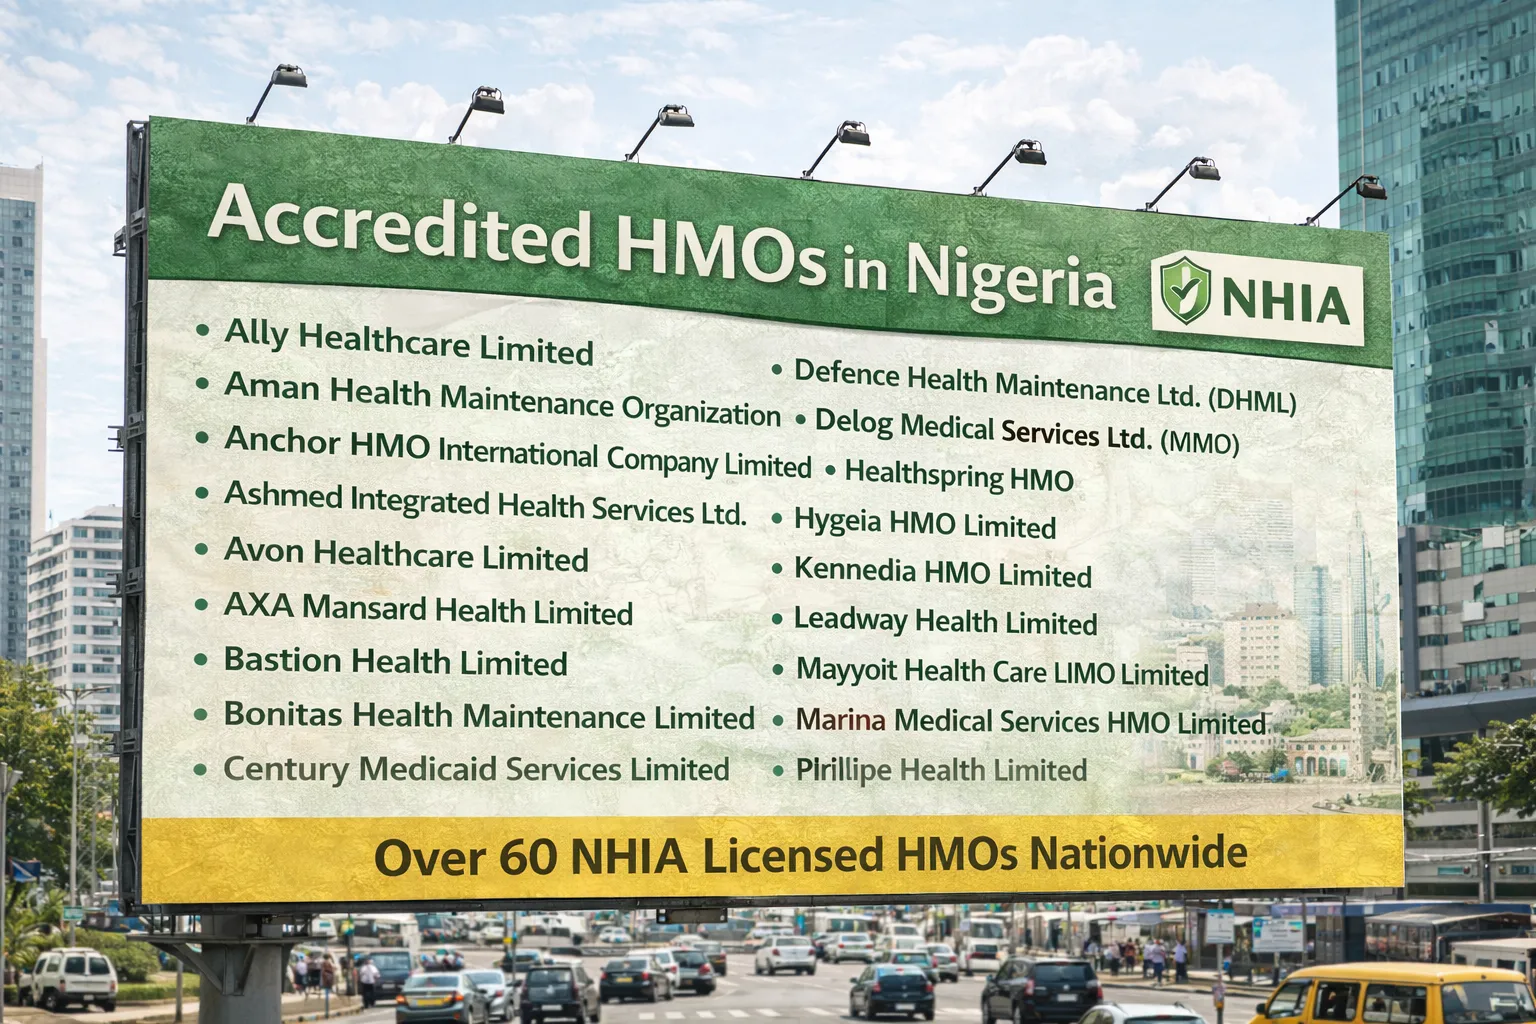
Step 1: Verify NHIA Accreditation Before Anything Else
This step is non negotiable.
Before you pay any HMO, visit:
Check the list here
Search for the exact name of the HMO.
Why is this critical?
Because enrolling with an unaccredited provider exposes you to:
Zero regulatory protection
Claim disputes without resolution
Financial loss
Poor accountability
Buying cheap insurance from a non accredited provider is not smart. It is risky.
Verification is your first shield against regret.
Step 2: Understand Your Personal Health Risk
Before shopping for cheap plans, ask yourself:
How often do I visit the hospital?
Do I have hypertension or diabetes?
Do I need maternity coverage soon?
Do I travel often?
Am I insuring just myself or my family?
If you rarely fall sick and only need basic outpatient care, a structured entry plan may work perfectly.
If you have a chronic condition, the cheapest plan may not be realistic.
Buying cheap without understanding your risk profile is like buying a small umbrella during storm season.
Think ahead.
Step 3: Compare at Least Three Accredited HMOs
Never buy the first cheap plan you see.
When learning How to Buy Cheap Health Insurance in Nigeria Without Regret, comparison is powerful.
Compare:
- Annual premium
- Hospital network size
- Inpatient admission cap
- Diagnostic coverage
- Drug coverage limits
- Emergency benefits
- Waiting periods
Sometimes one plan is slightly more expensive but offers double the inpatient coverage.
That small price difference can prevent major regret.
Step 4: Watch for Hidden Costs
Hidden costs are the number one cause of regret.
Ask clearly before enrolling:
Are there copayments?
What percentage do I pay for lab tests?
Is there an annual cap on surgeries?
Are specialist consultations limited?
Are some drugs excluded?
A cheap plan with heavy copayments may cost more during illness.
Always request the full benefit schedule in writing.
Transparency prevents disappointment.
Step 5: Choose a Hospital You Can Actually Reach
A cheap plan is useless if the only covered hospital is two hours away.
When selecting your HMO:
Choose hospitals close to home.
Check emergency accessibility.
Confirm that the hospital is active within the HMO network.
Convenience becomes critical during emergencies.
Distance creates stress.
Step 6: Understand Waiting Periods Clearly
Many cheap plans include waiting periods for:
Maternity services
Pre existing conditions
Certain surgeries
Always ask:
When does coverage start?
Are there exclusions during the first few months?
If you ignore waiting periods, regret becomes likely.
Clarity protects you.
Step 7: Buy Directly from Official Channels
To Buy Cheap Health Insurance in Nigeria Without Regret:
Avoid random WhatsApp sellers.
Avoid cash transfers without documentation.
Avoid social media ads without verification.
Always:
- Use the official agents or HMO website.
- Get email confirmation.
- Keep your payment receipts.
- Save your membership or enrollee number on your phone.
Proper documentation equals protection.
Common Regret Scenarios Nigerians Face
These are common statements people make after buying the wrong plan:
“I did not know maternity was excluded.”
“I did not check the inpatient cap.”
“I assumed my hospital was covered.”
“I did not verify accreditation.”
“I chose based only on price.”
Every single one of these regrets was avoidable.
Smart buying eliminates regret.
Health insurance mistakes are expensive.
Inside this powerful guide, I break down the 20 most common mistakes Nigerians make when choosing health insurance and show you exactly how to avoid them like a pro.
If you want clarity before commitment, this ebook is for you.
Who Should Consider Entry Level Cheap Plans
These plans are ideal for people who want affordable health coverage for basic medical needs such as consultations, minor treatments, and essential medications without paying for extensive premium benefits.
They provide financial protection at a lower cost while still giving access to accredited hospitals within the HMO provider network.
Entry level plans are often suitable for:
Students
NYSC members
Young professionals
Freelancers
Low risk individuals
If you are generally healthy and need basic outpatient coverage, cheap plans can work well.
But if you anticipate major medical needs, consider upgrading.
Be realistic, not optimistic.
How to Balance Cheap and Comprehensive Coverage
Never compromise on:
Emergency coverage
Hospital accessibility
Reasonable inpatient limits
NHIA accreditation
You can compromise on:
Luxury hospital preferences
Extra specialist add ons
Extended brand drug lists
Smart balance ensures affordability without regret.
FAQs
- Is the cheapest health insurance plan always the smartest choice?
No.
The cheapest plan is only smart if it covers your most likely medical needs. If you rarely need hospital admission and mainly require consultations and basic medication, an entry level plan may work perfectly.
However, if you:
Have chronic illness
Plan for maternity soon
Travel often
Want access to top tier hospitals
Then the cheapest option may lead to regret.
The smartest plan is the one that fits your risk profile, not just your wallet.
- How do I know if a cheap HMO plan will actually pay hospitals?
Start by confirming accreditation via the NHIA website
Then check:
Online reviews
Hospital feedback
Customer service responsiveness
Claim reputation
You can also call one or two hospitals in the network and ask about their experience with the HMO.
Direct confirmation gives peace of mind.
- What is the biggest mistake people make when buying cheap health insurance?
The biggest mistake is ignoring coverage caps.
For example:
If your inpatient limit is low and your surgery exceeds that limit, you will pay the difference out of pocket.
Always check:
Annual inpatient cap
Per illness cap
Emergency coverage limit
Specialist visit limits
Numbers matter more than price tags.
- Can I start with a cheap plan and upgrade later?
Yes.
Most HMOs allow plan upgrades during renewal or mid cycle with additional payment.
Starting cheap is not a problem.
Staying uninformed is.
If your circumstances change, upgrade responsibly.
- Is buying cheap health insurance online safe in Nigeria?
Yes, if done correctly.
To stay safe:
Use official HMO websites only.
Verify accreditation.
Ensure the website uses secure connection.
Keep payment confirmation.
Avoid unofficial agents.
Online purchase is secure when verification is prioritized.
- What happens if I exceed my coverage limit?
If your treatment cost exceeds your coverage cap, you pay the balance.
That is why checking inpatient and surgical limits is critical before enrollment.
Cheap plans usually have lower caps.
Know the numbers before committing.
- Should I buy cheap insurance for my parents?
Be cautious.
Older adults typically require:
Higher inpatient limits
Chronic condition management
Specialist access
Cheap entry plans may not be sufficient for elderly parents.
Match coverage to age related risk.
- How do I avoid emotional buying decisions?
Pause before paying.
Ask:
Does this plan cover my real needs?
Is the hospital convenient?
Have I verified accreditation?
Have I read the full benefit schedule?
If you cannot answer confidently, do not proceed.
Confidence reduces regret
Conclusion
Learning How to Buy Cheap Health Insurance in Nigeria Without Regret is about strategy, not shortcuts.
- Verify accreditation.
- Understand your health needs.
- Compare providers.
- Read benefit schedules carefully.
- Check coverage caps.
- Avoid hidden fees.
- Buy directly from official sources.
Cheap can protect you.
Cheap can save you money.
Cheap can give peace of mind.
But only when it is smart.
| |||||||||||
| Odilo Alexander (Editor-in-Chief) is a registered Nurse RN BSN trained at the University of Benin and licensed by the Nursing and Midwifery Council of Nigeria. With over eight years of experience across clinical and managed care settings including leadership roles in claims management and HMO operations, AOBLOG provides practical and evidence based wellness and health insurance education for Africa. |